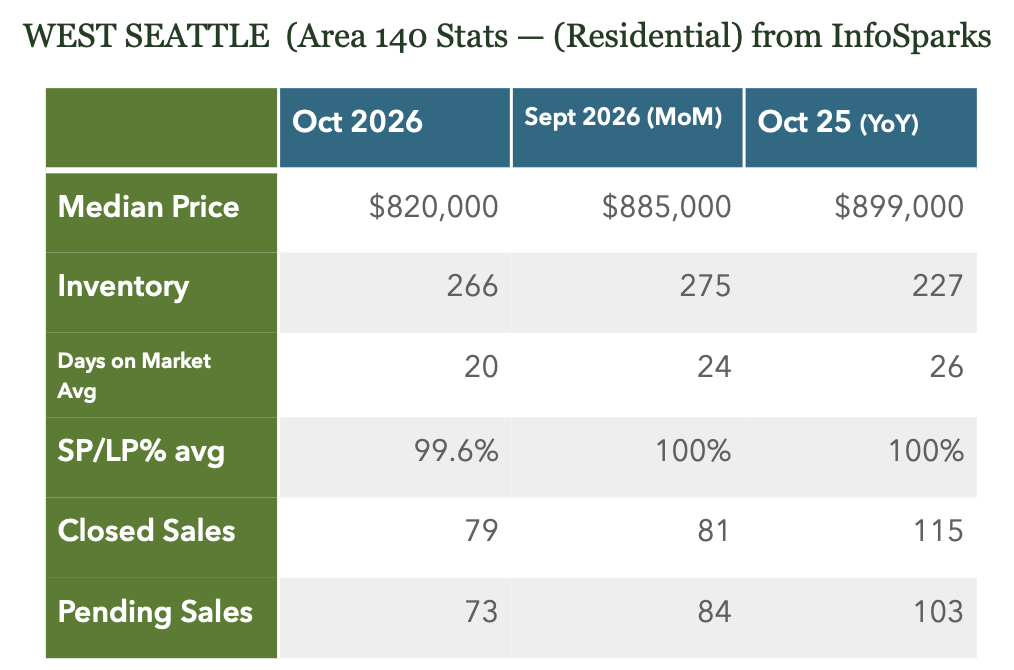
With September and October in the books, we can get a better picture of the fall market and it was less active than previous years. Fall can often be the second busiest time of the year in real estate, with Spring (especially March and April) being the busiest. Fall markets historically have an increase in Sales and Median Price as there are more new listings and stronger demand than in July and August. September’s numbers were up over the previous months and generally that has some carry over into October. But this year (in West Seattle) we saw a fairly big drop in Median, Closed Sales and Pending Sales in October. Inventory remains elevated and Final Sales Price/List Price ratios slightly dropped. Higher interest rates (near 7.5%), local area layoffs and election uncertainty are likely culprits. We would expect these trends (lower Median, less Pending and Closed Sales) and higher inventory numbers to continue over the next couple of months.
Median Price has been marked by peaks and valleys this year. Some of it can be attributed to seasonal trends or reactions to geopolitical events or to the bumpy interest rate environments.
Some home sales remain competitive as 18 listings received over 100% of list price which is about the same as last year (20). 23 homes closed with less than 100% and 38 right 100%. Average Sales Price saw a big drop from a year ago, $1.04M to $877,609. We saw less higher priced homes selling last month, 21 of the 79 had sales prices over 1M, compared to 35 last October.
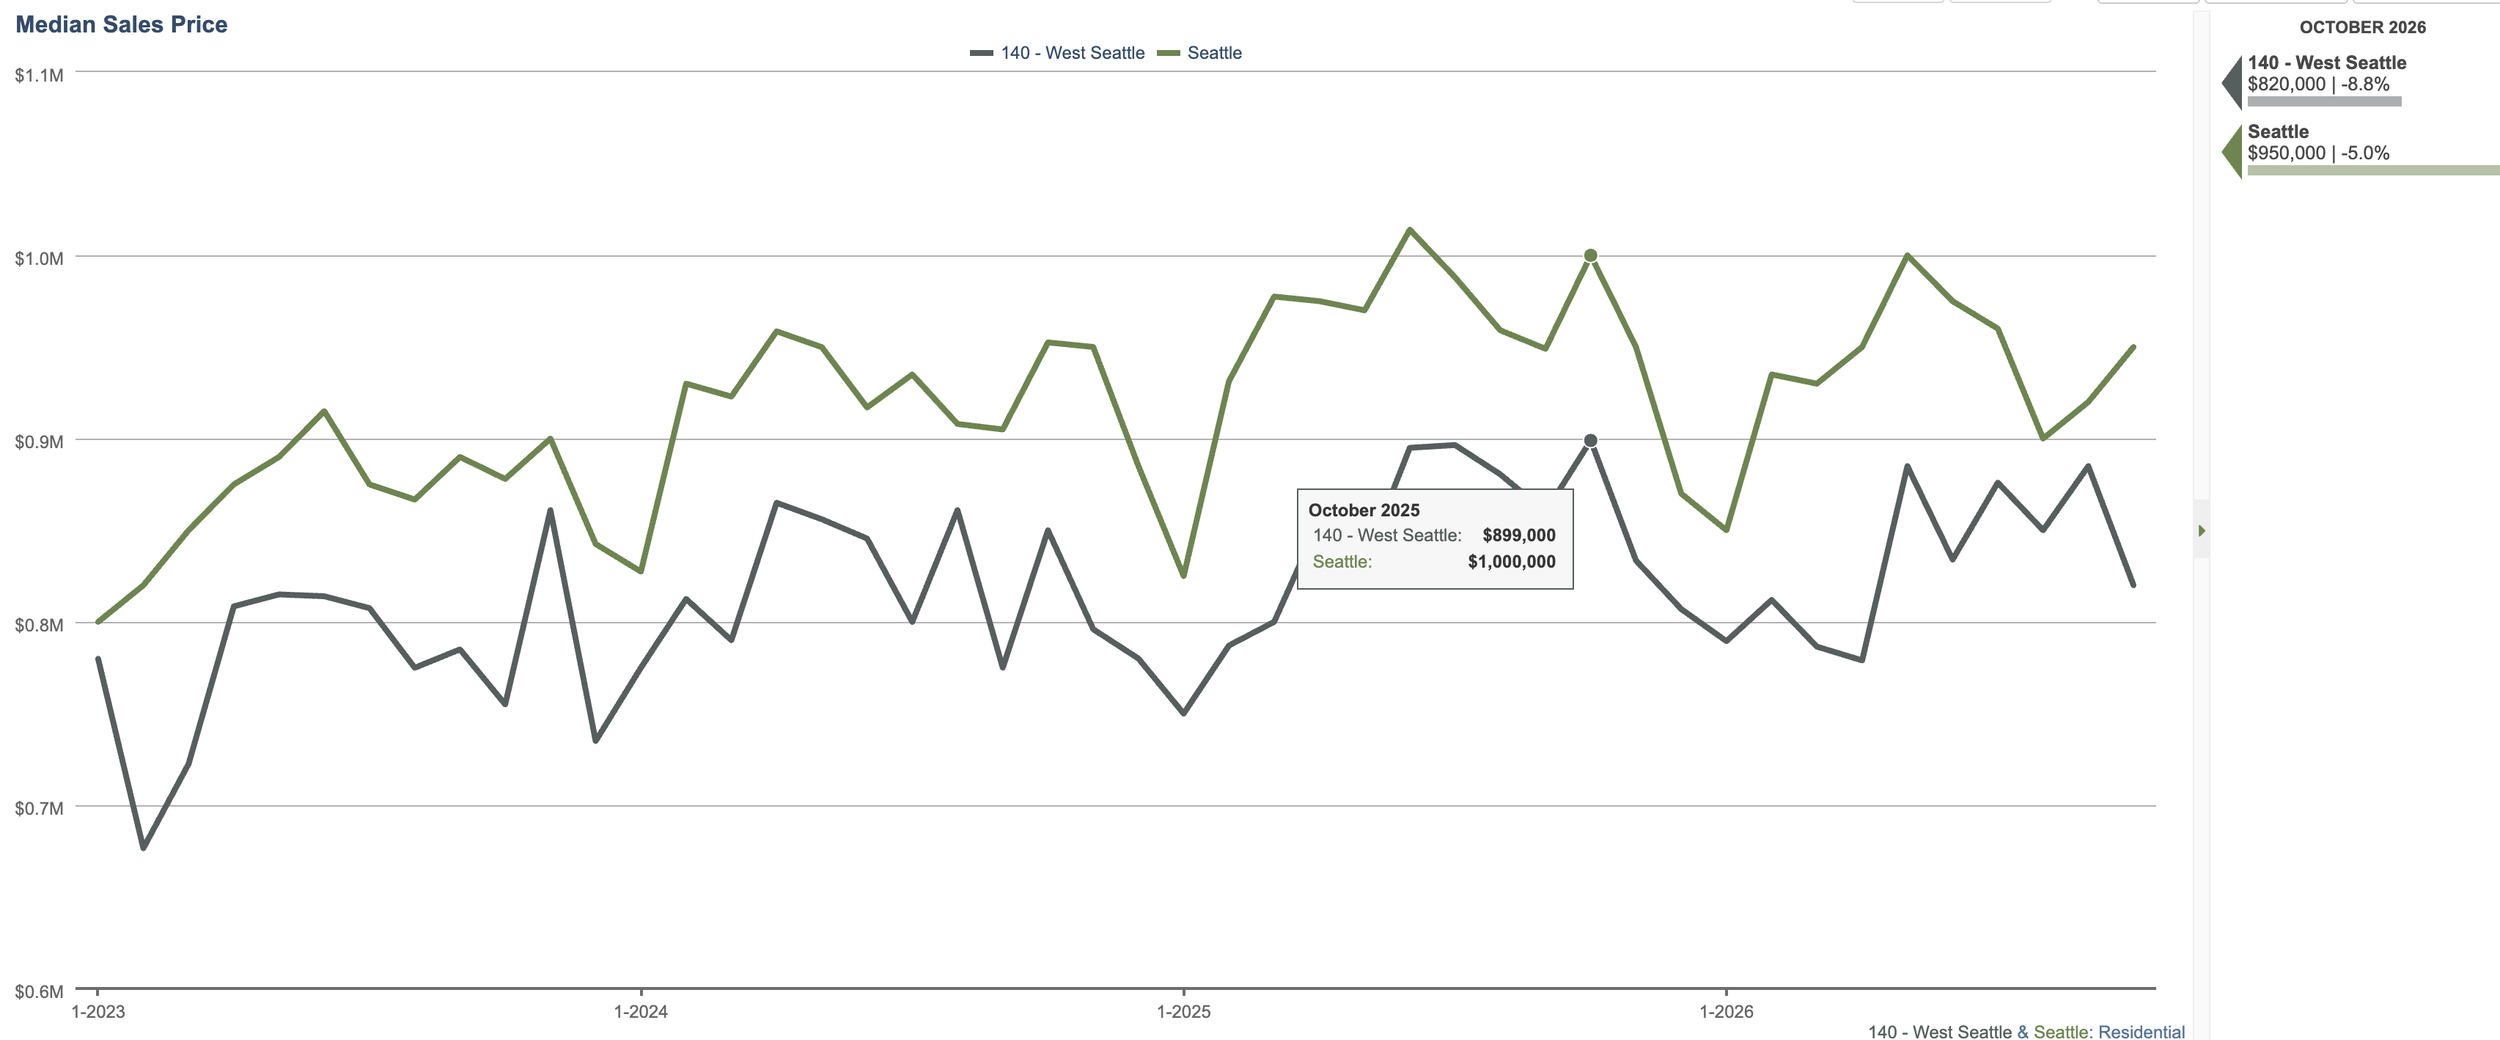
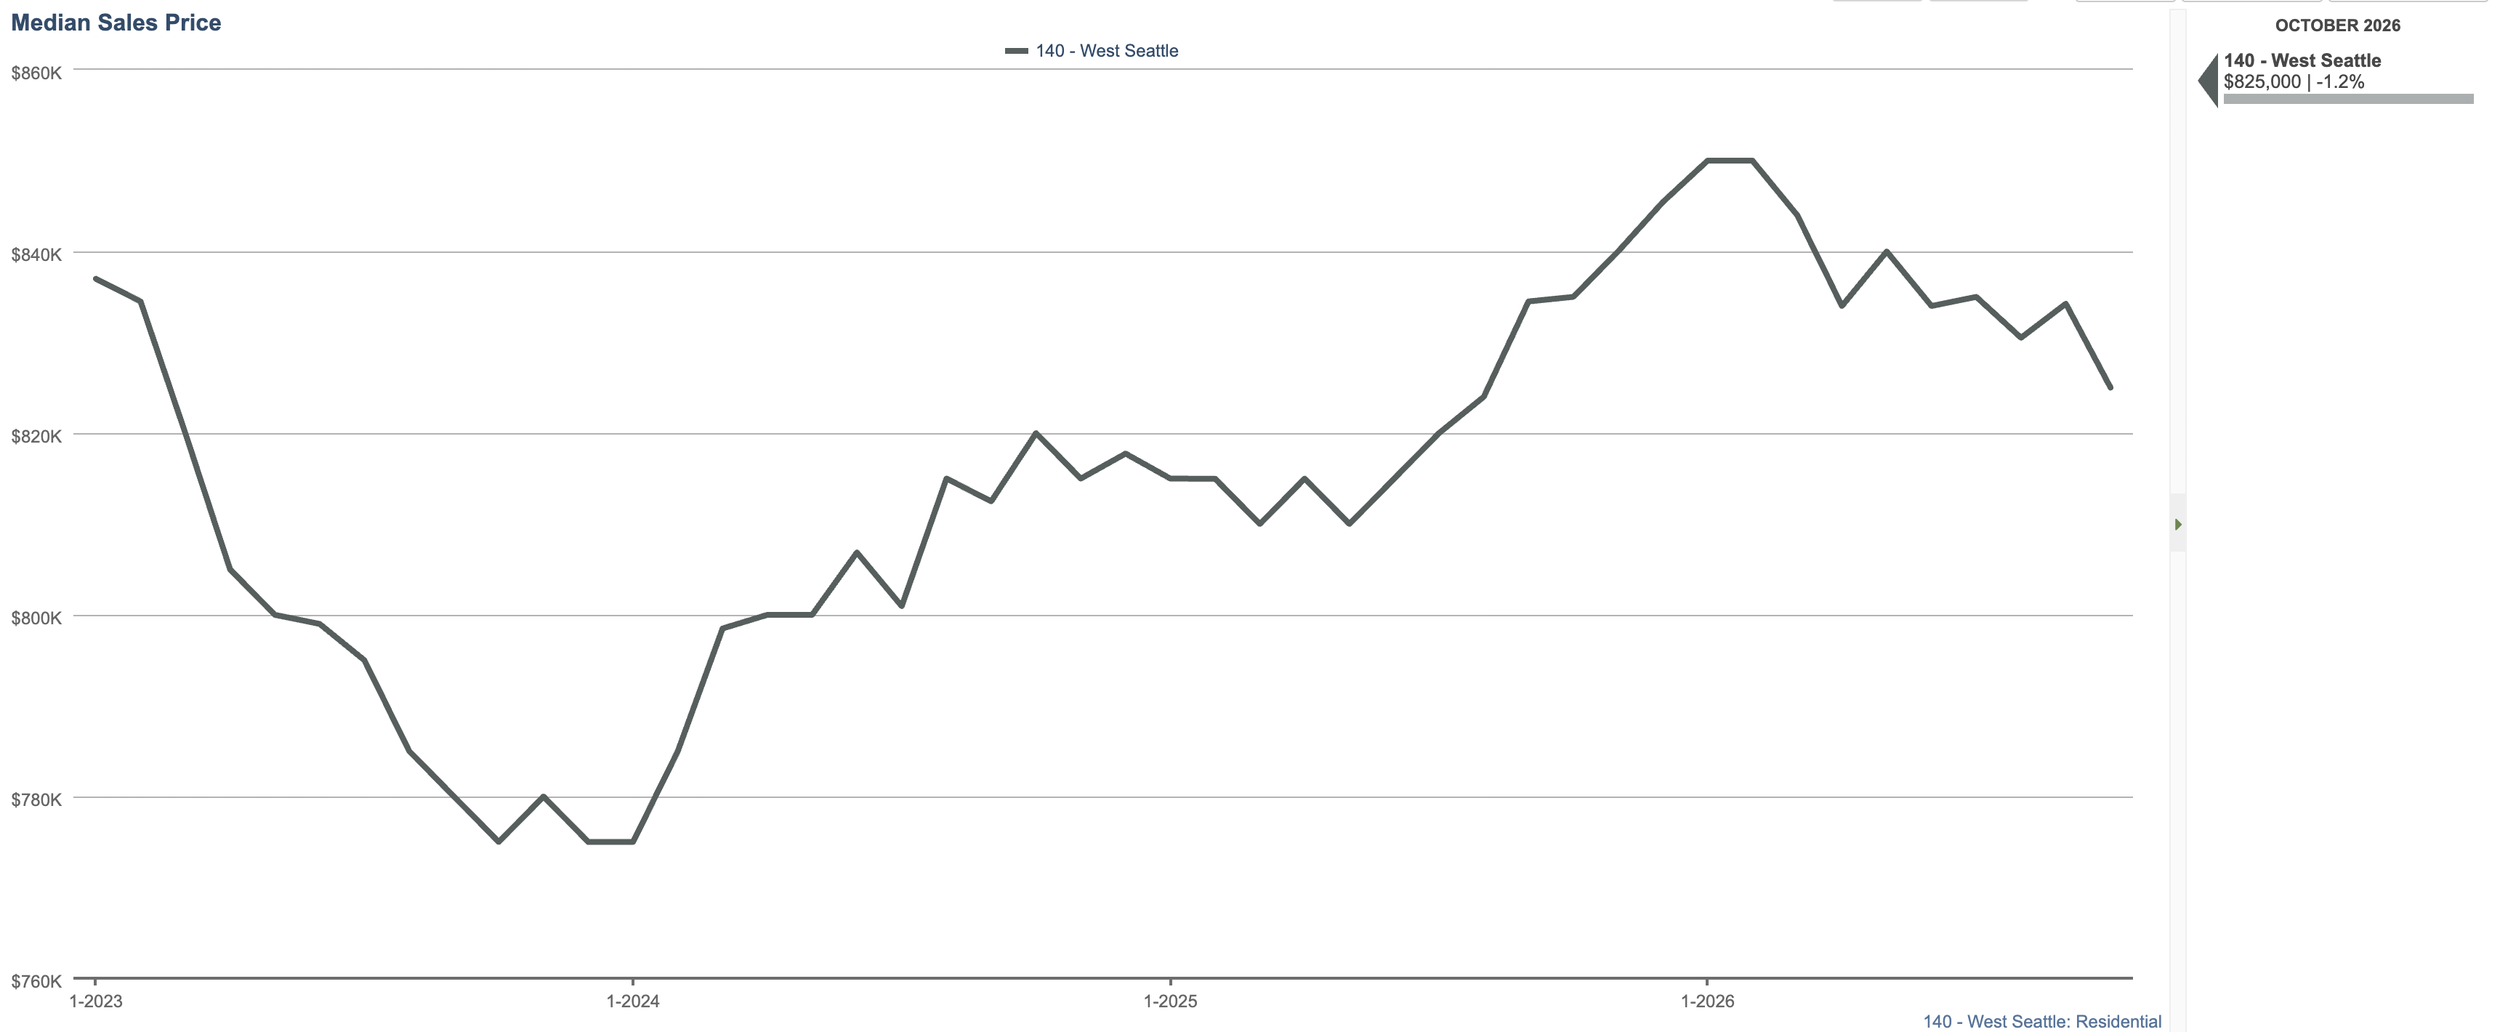
The previous graph shows monthly data points and can show us what months are more active. The below graph shows a rolling 12 month average (it smooths out the peaks and valleys) and definitely shows a downward trend in pricing over the past year.
Here is a chart of interest rates the past 5 years. The market adjusted after the aggressive hikes in 2022 but coupled with higher inflationary numbers (gas, food, health care) but it seems consumers have halted the rising Median Price in 2026 (West Seattle).
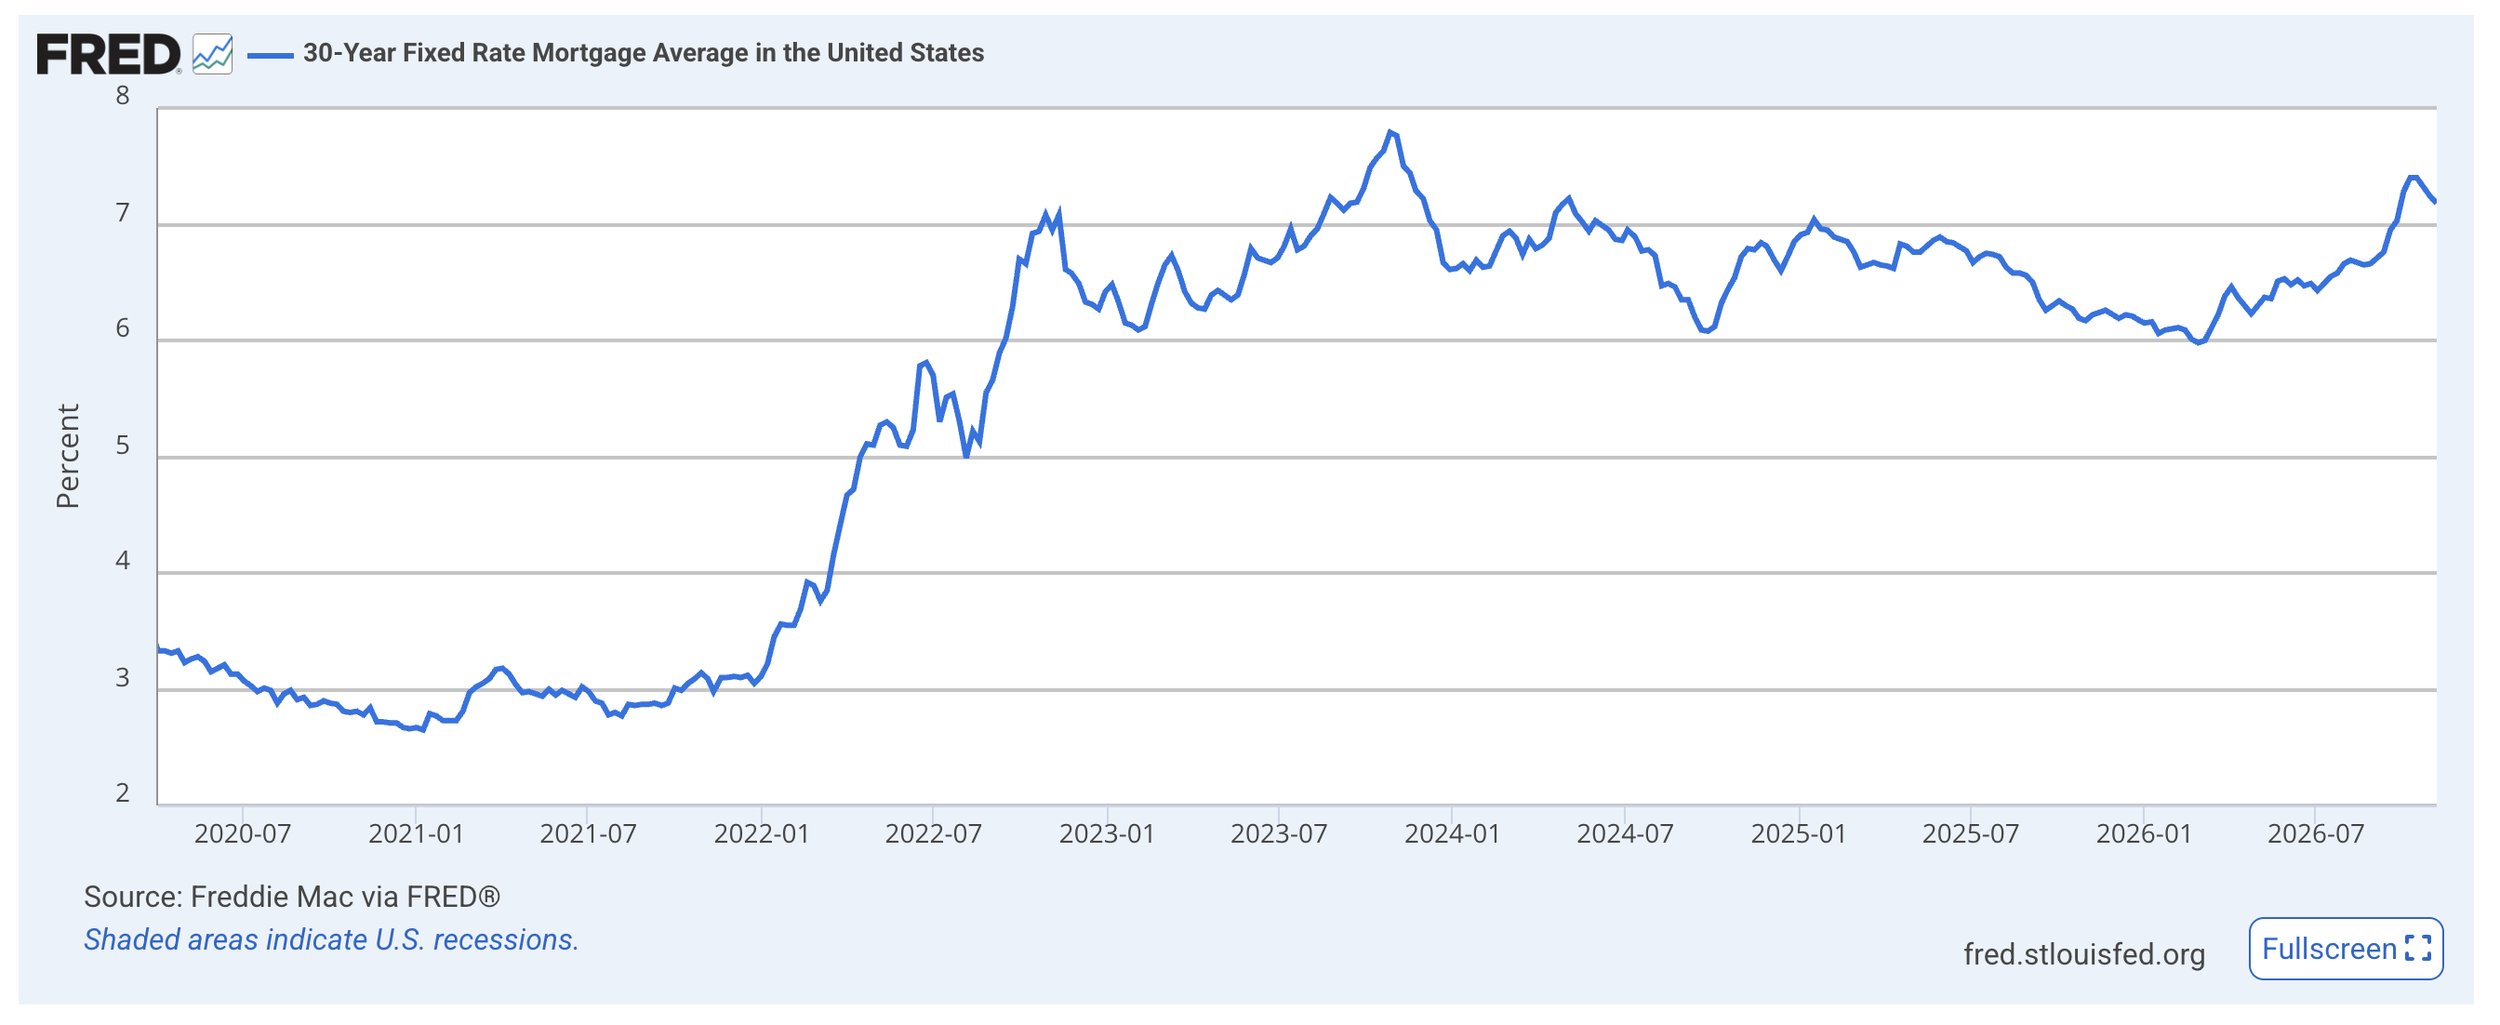
Freddie Mac, 30-Year Fixed Rate Mortgage Average in the United States [MORTGAGE30US], retrieved from FRED, Federal Reserve Bank of St. Louis; https://fred.stlouisfed.org/series/MORTGAGE30US, November 6, 2026.
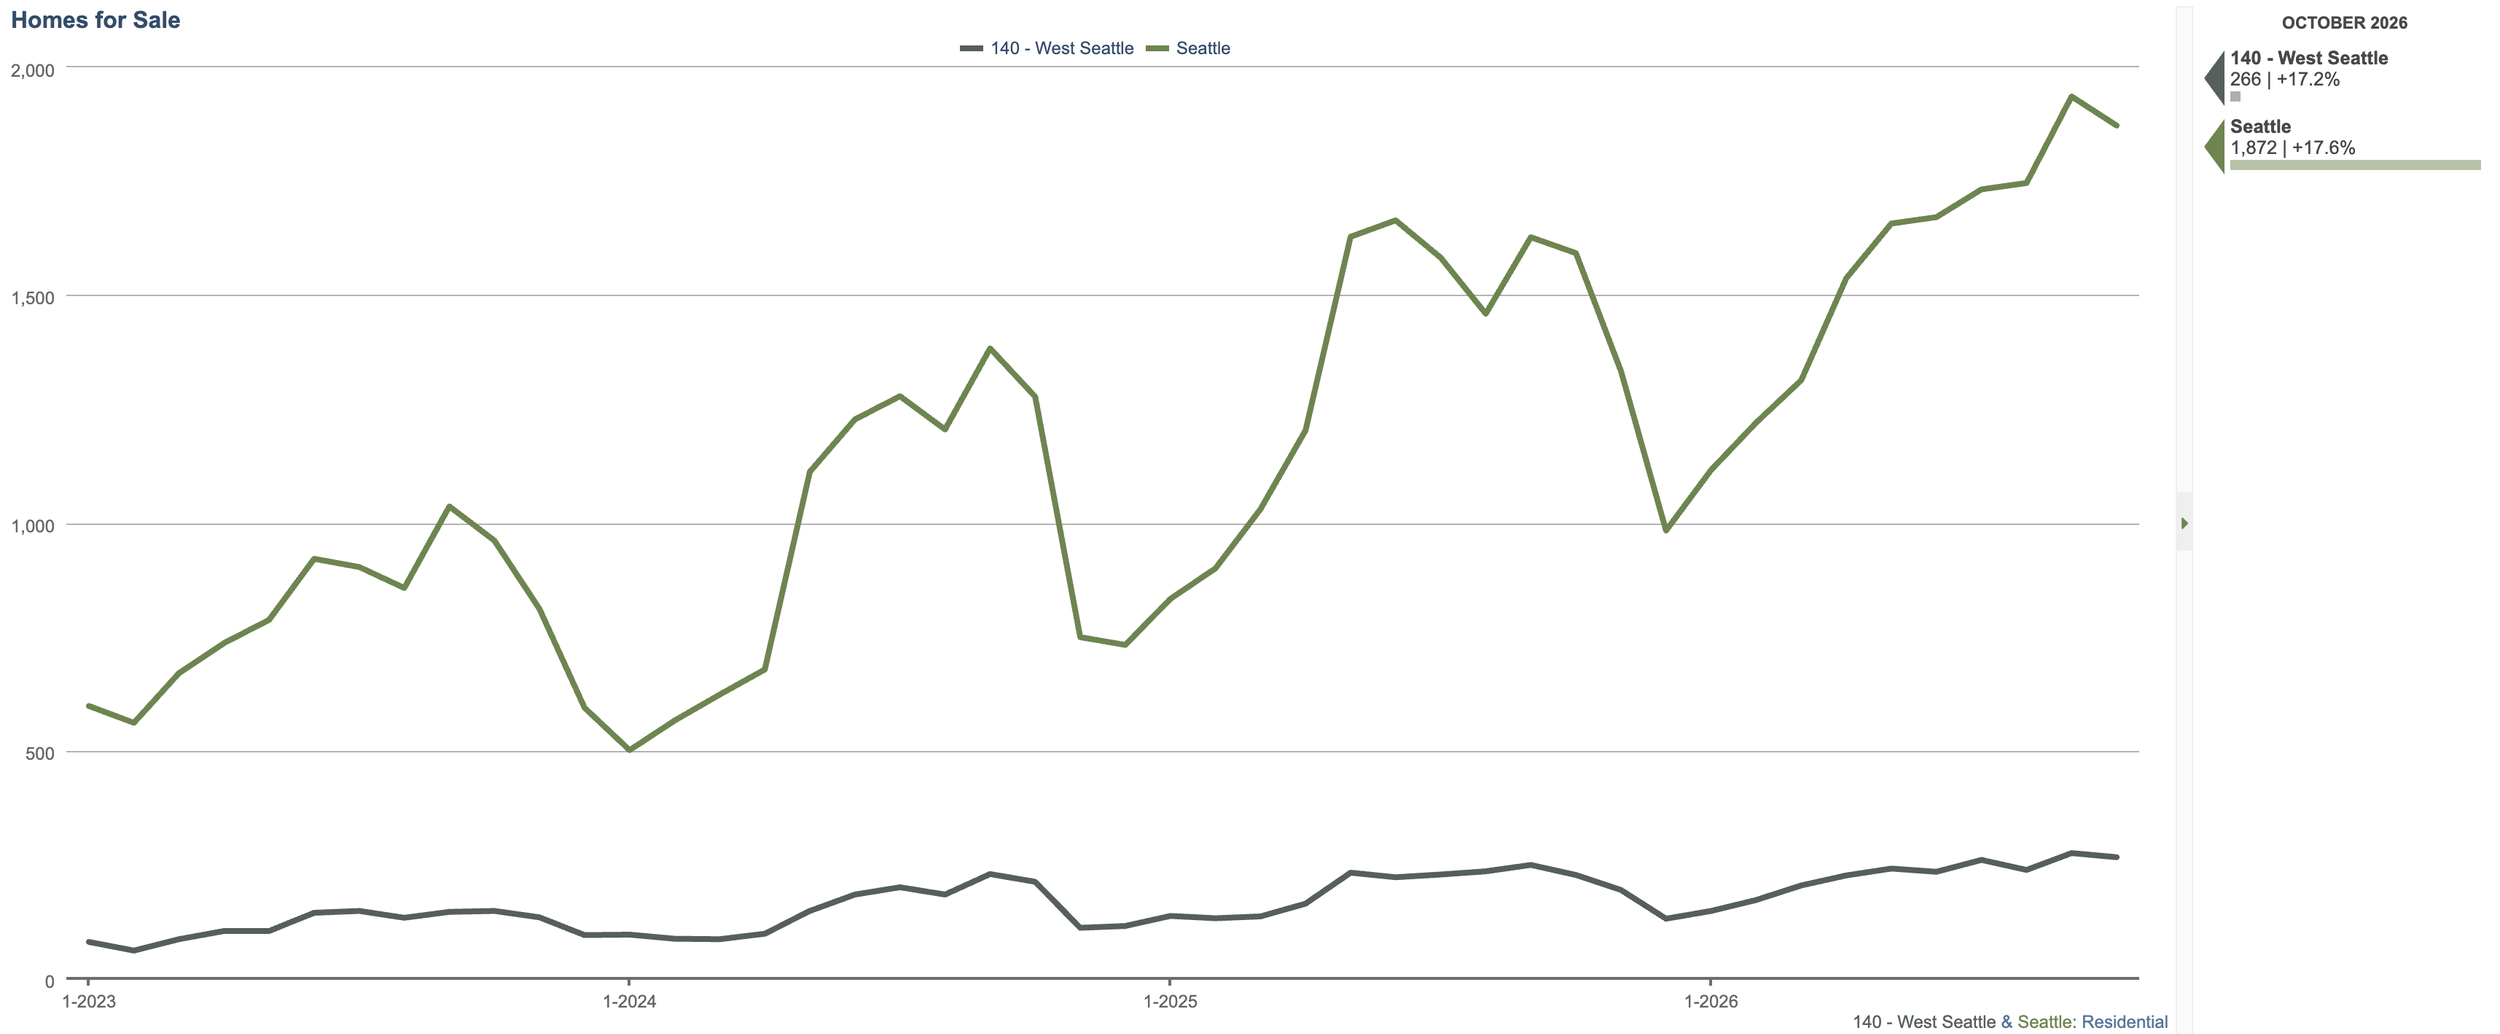
Inventory was flat last month (and over YoY) and we would expect this to stay about the same in November and then drop in December and January. We typically see less New Listings in November-January and then New Listings start hitting the market March-May (when demand if higher). The Spring Market is typically pretty strong (more demand and new fresh inventory) but there is some uncertainty if 2027 will perform as previous seasons. We might see more sales but maybe not the huge price increases.
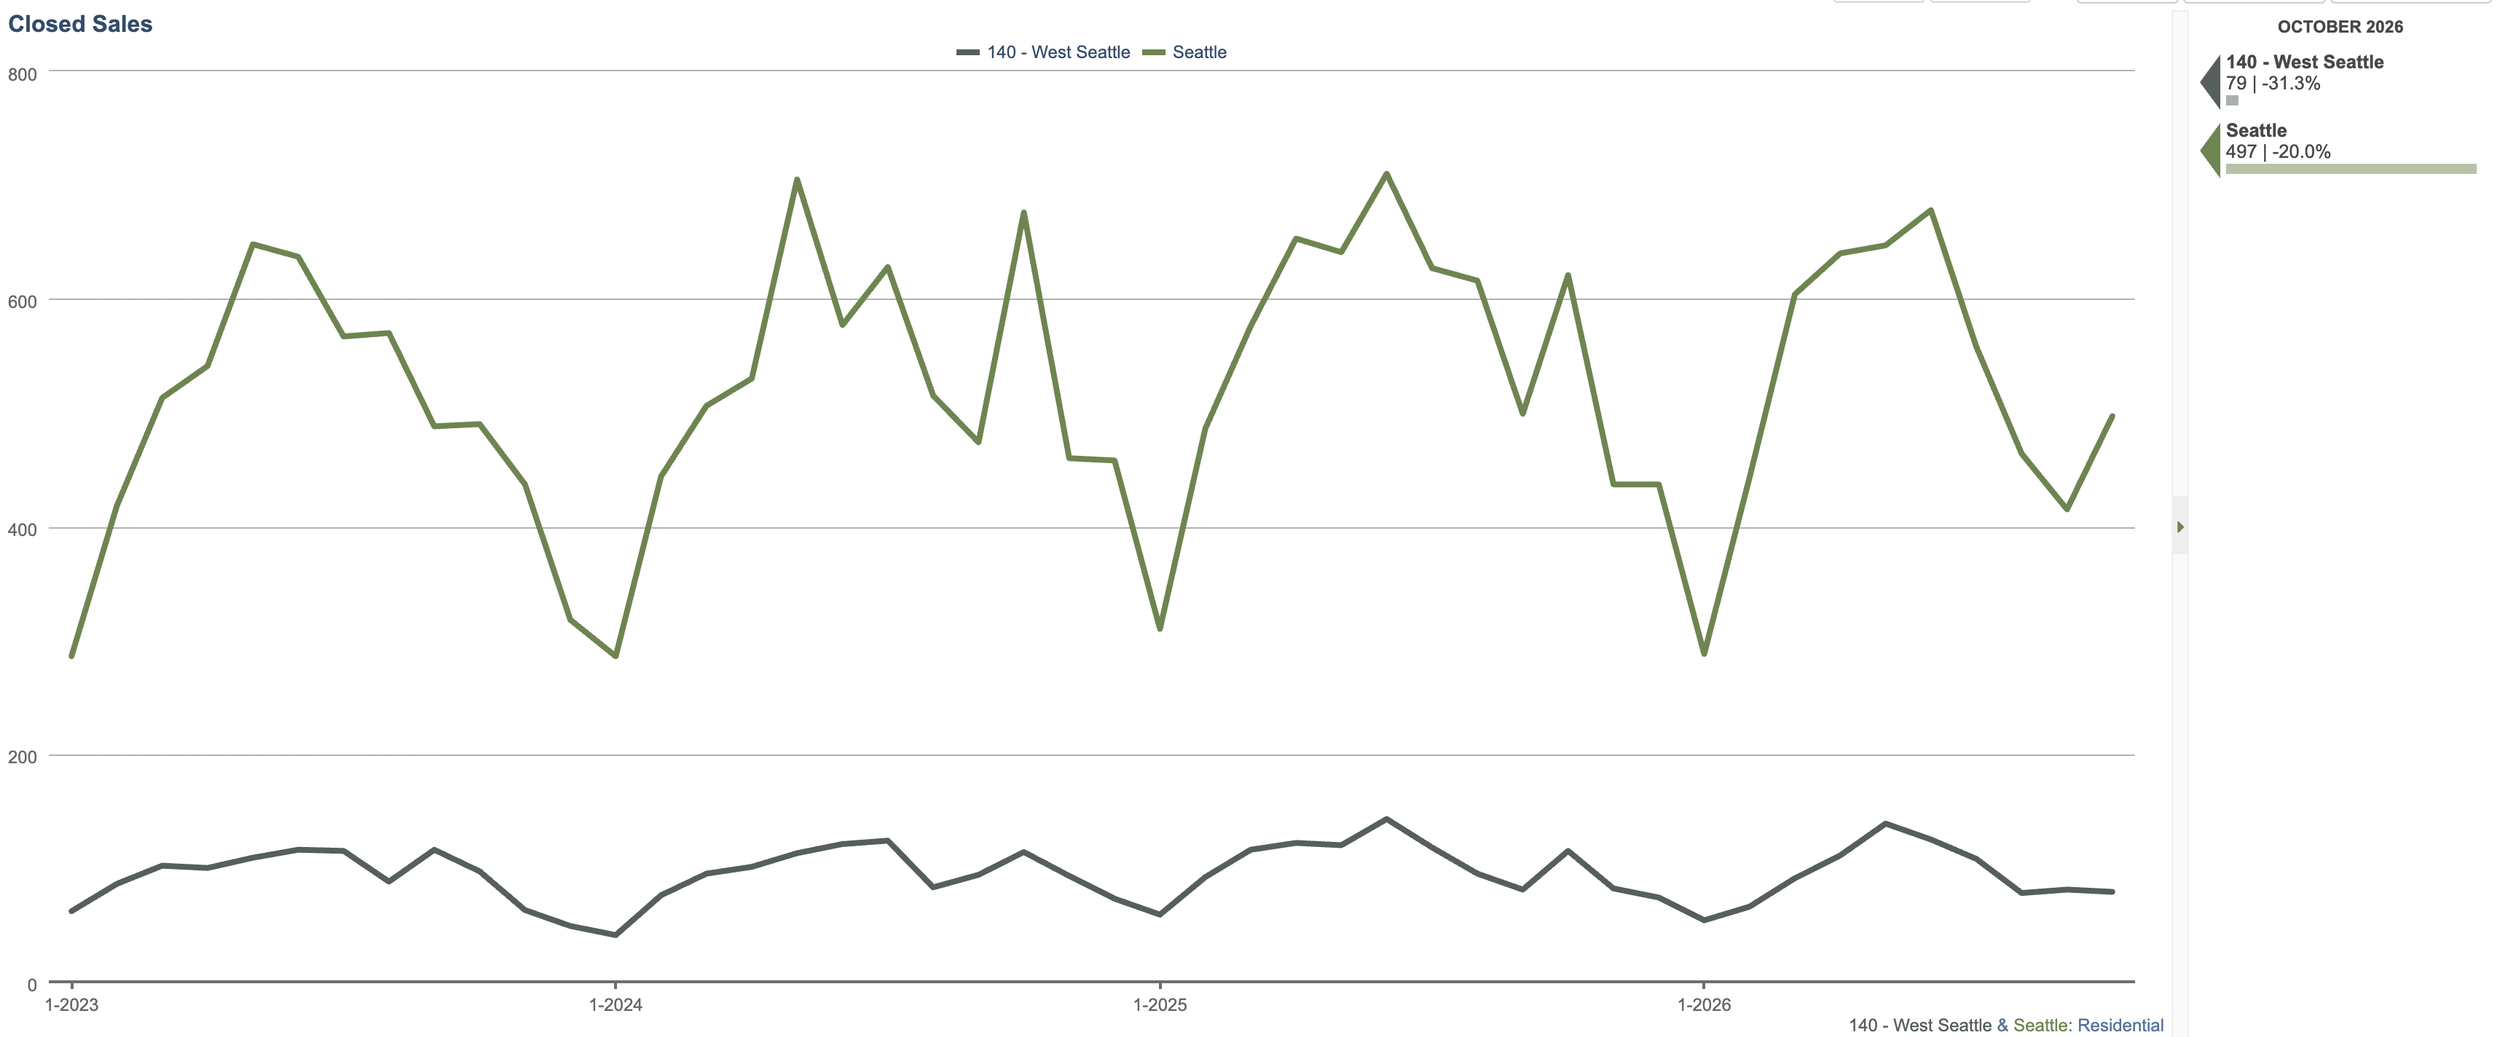
Closed Sales were mostly flat last month. Closed sales are often a reflection of the previous month (as it can take a month to close a transaction) so this is an indicator this September-October market were slower than previous fall markets.
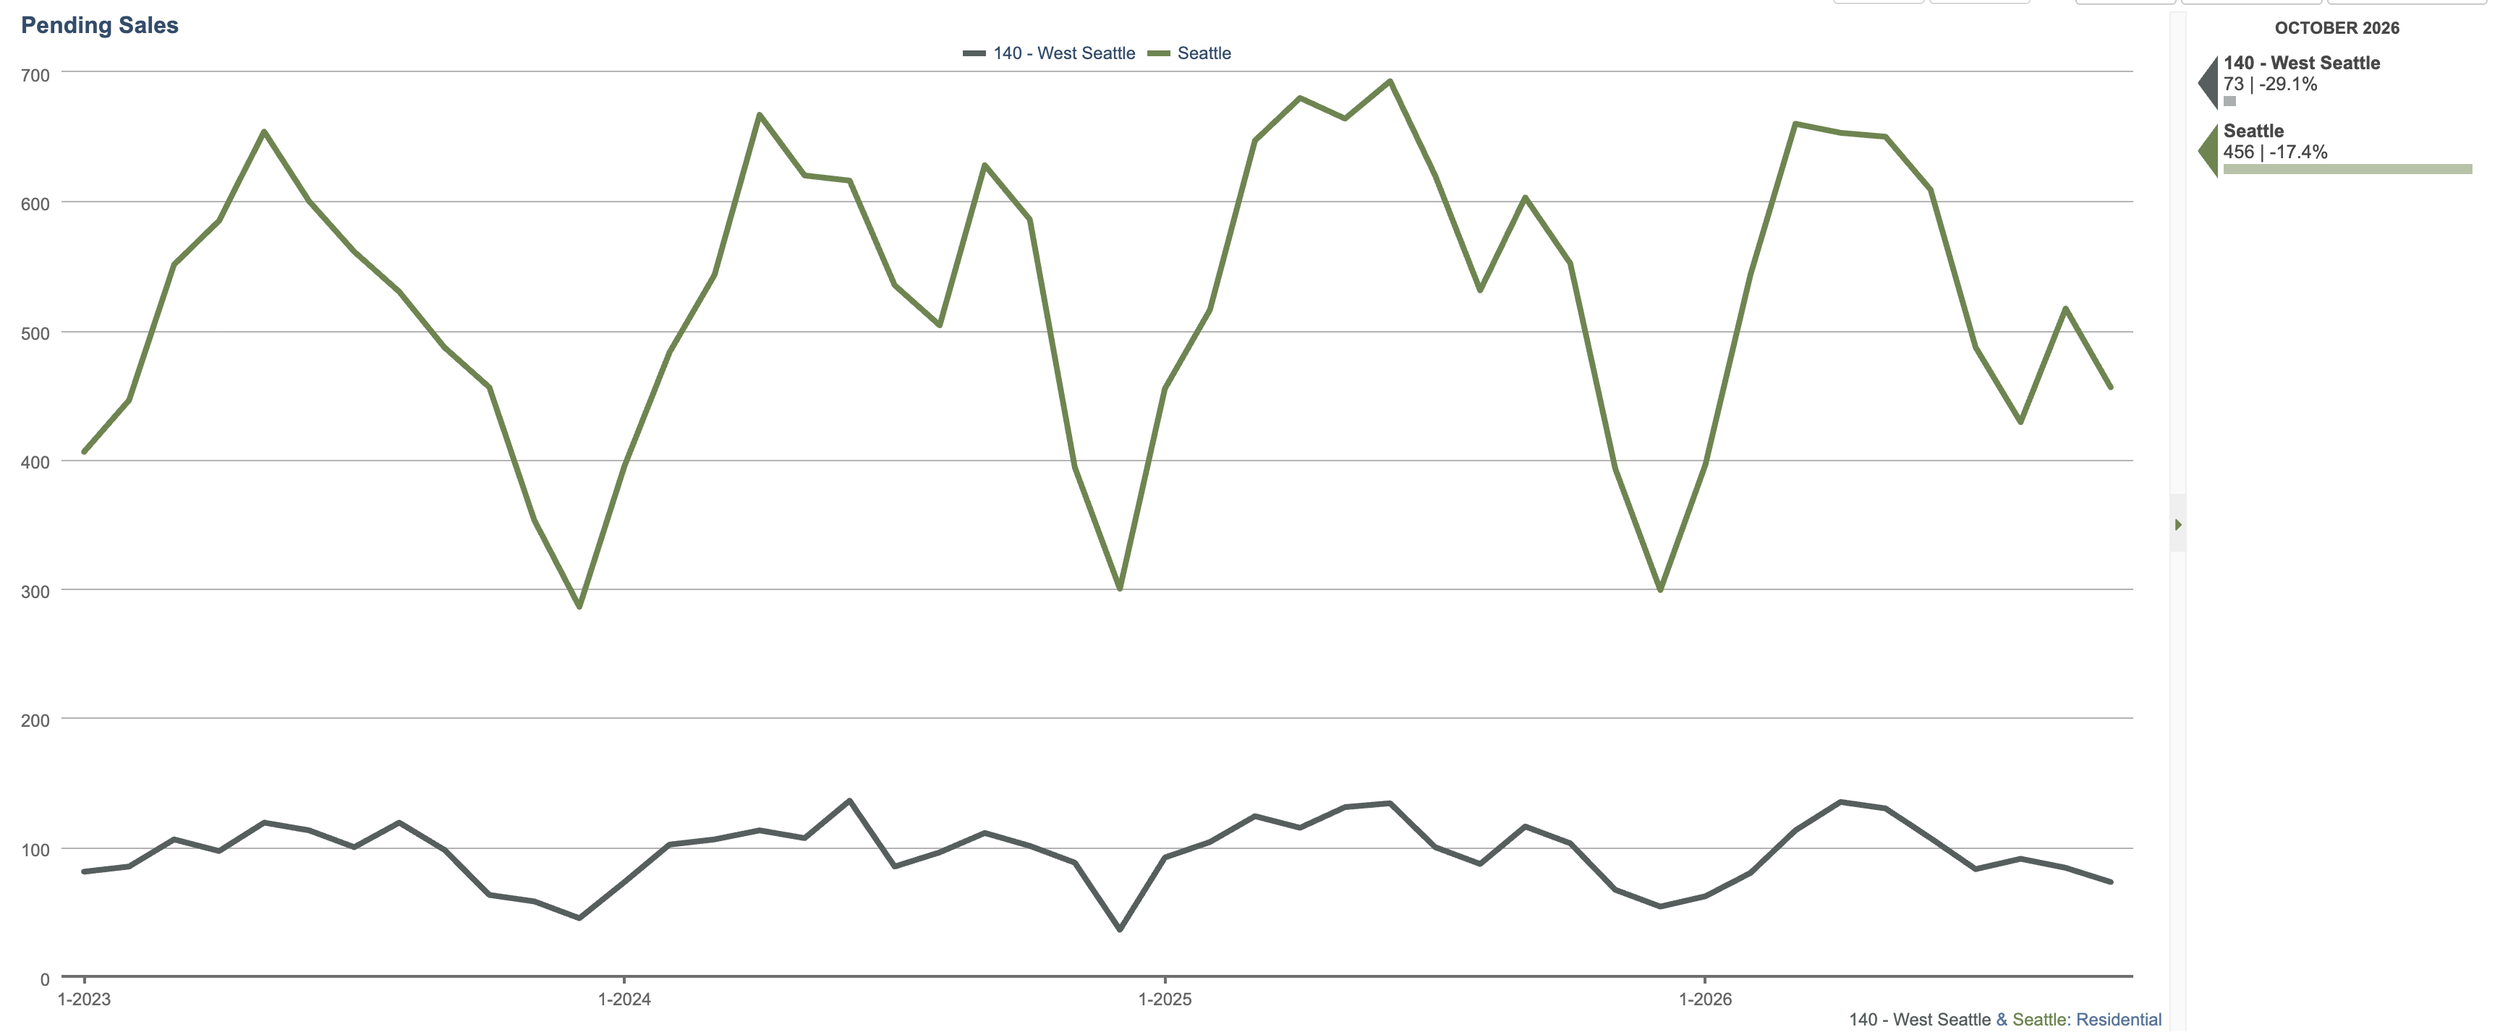
Pending Sales dipped in October. We would expect that number to continue as we get into winter. There is less new inventory and buyer’s attention turns to other things.
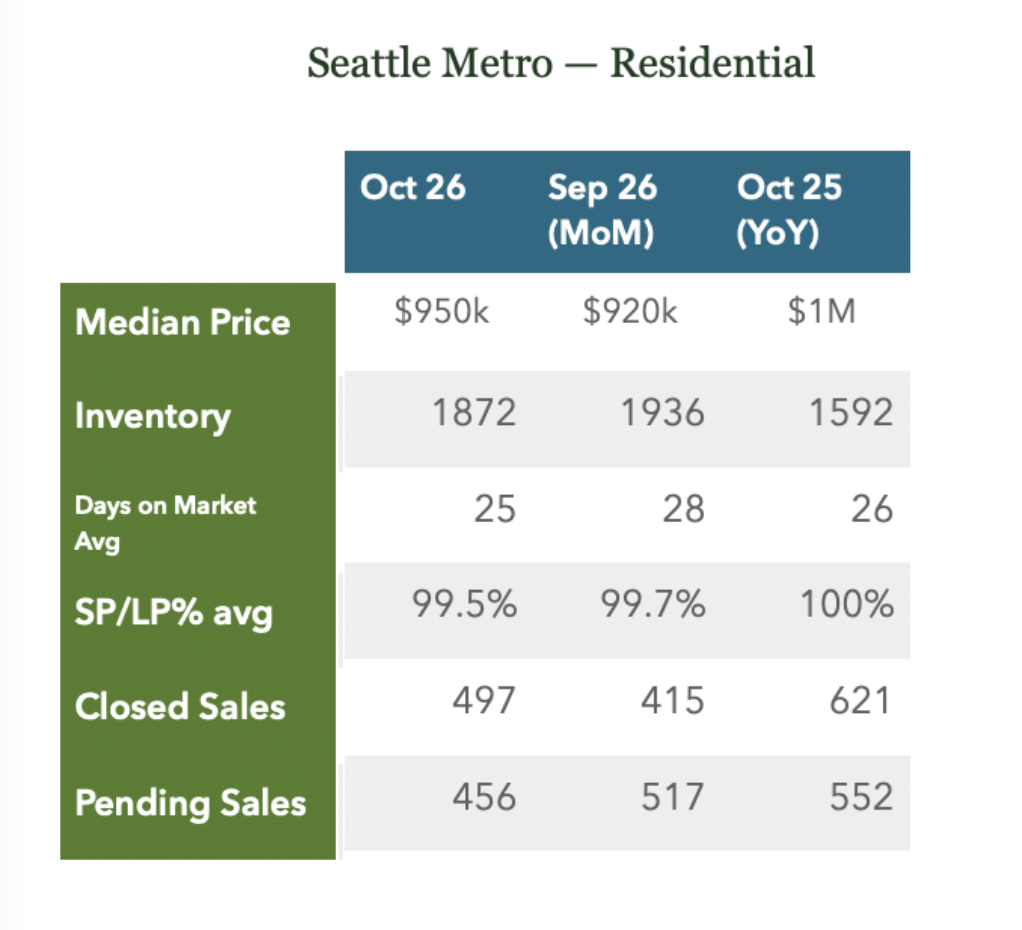
Seattle Metro saw a more traditional fall bump MoM but well off of the previous year. Inventory is high, Pending and Closed Sales are down from the previous year. About a quarter of the existing inventory, 465 of 1872, is considered New Construction. Demand for that product is not as strong as a detached existing house, which segment remains fairly strong. Especially homes that are turn-key and in better locations.